Latest from BCA Research

Expectations for US inflation at 3.3 percent are inconsistent with expectations for the Fed to slash rates, so one of these expectations is likely wrong. We describe how to play this mispricing. Plus, a new position is to go overweight global consumer discretionary (RXI).

Chinese stock prices have significantly decoupled from the country’s business cycle, with the full impact of US tariffs yet to be realized. The valuation-driven equity gains without a cyclical economic recovery will be vulnerable to a reversal.


Markets have ripped in July, ignoring underwhelming payrolls and retail sales figures. This was our bet, so we don't think this is a mistake. The economy is transitioning from one catalyzed by cash to one led by lower borrowing rates. The combination of a growth slowdown tempered fiscal policy, and an uber-dovish Fed is good for bonds and equities, which has not yet been priced by markets.

In our Beta report, we introduce a new framework for thinking about long-term investing in a multipolar world: The Garrison State. Investors need to shed their outdated view that geopolitical risks are... a risk. History teaches us that pressure makes diamonds. And geopolitical pressure makes Garrison States, which tend to outperform precisely because by definition, the bevy of risks that surrounds them is existential.


The US High Quality (USHQ) portfolio underperformed its benchmark through July, returning -1.5%, whilst its SPY benchmark returned 0.2%. On a trailing three-month basis, performance was notably weak vs. benchmark, with USHQ underperforming by approx. 750bps.

Copper’s unwind – triggered by the refined metal’s US tariff exemption – isn’t over yet. We remain short the red metal on an absolute basis and relative to gold.

We maintain our 12-month US recession probability at 60%. However, until the “whites of the recession’s eyes” are more clearly visible, we would refrain from moving to a fully defensive stance.
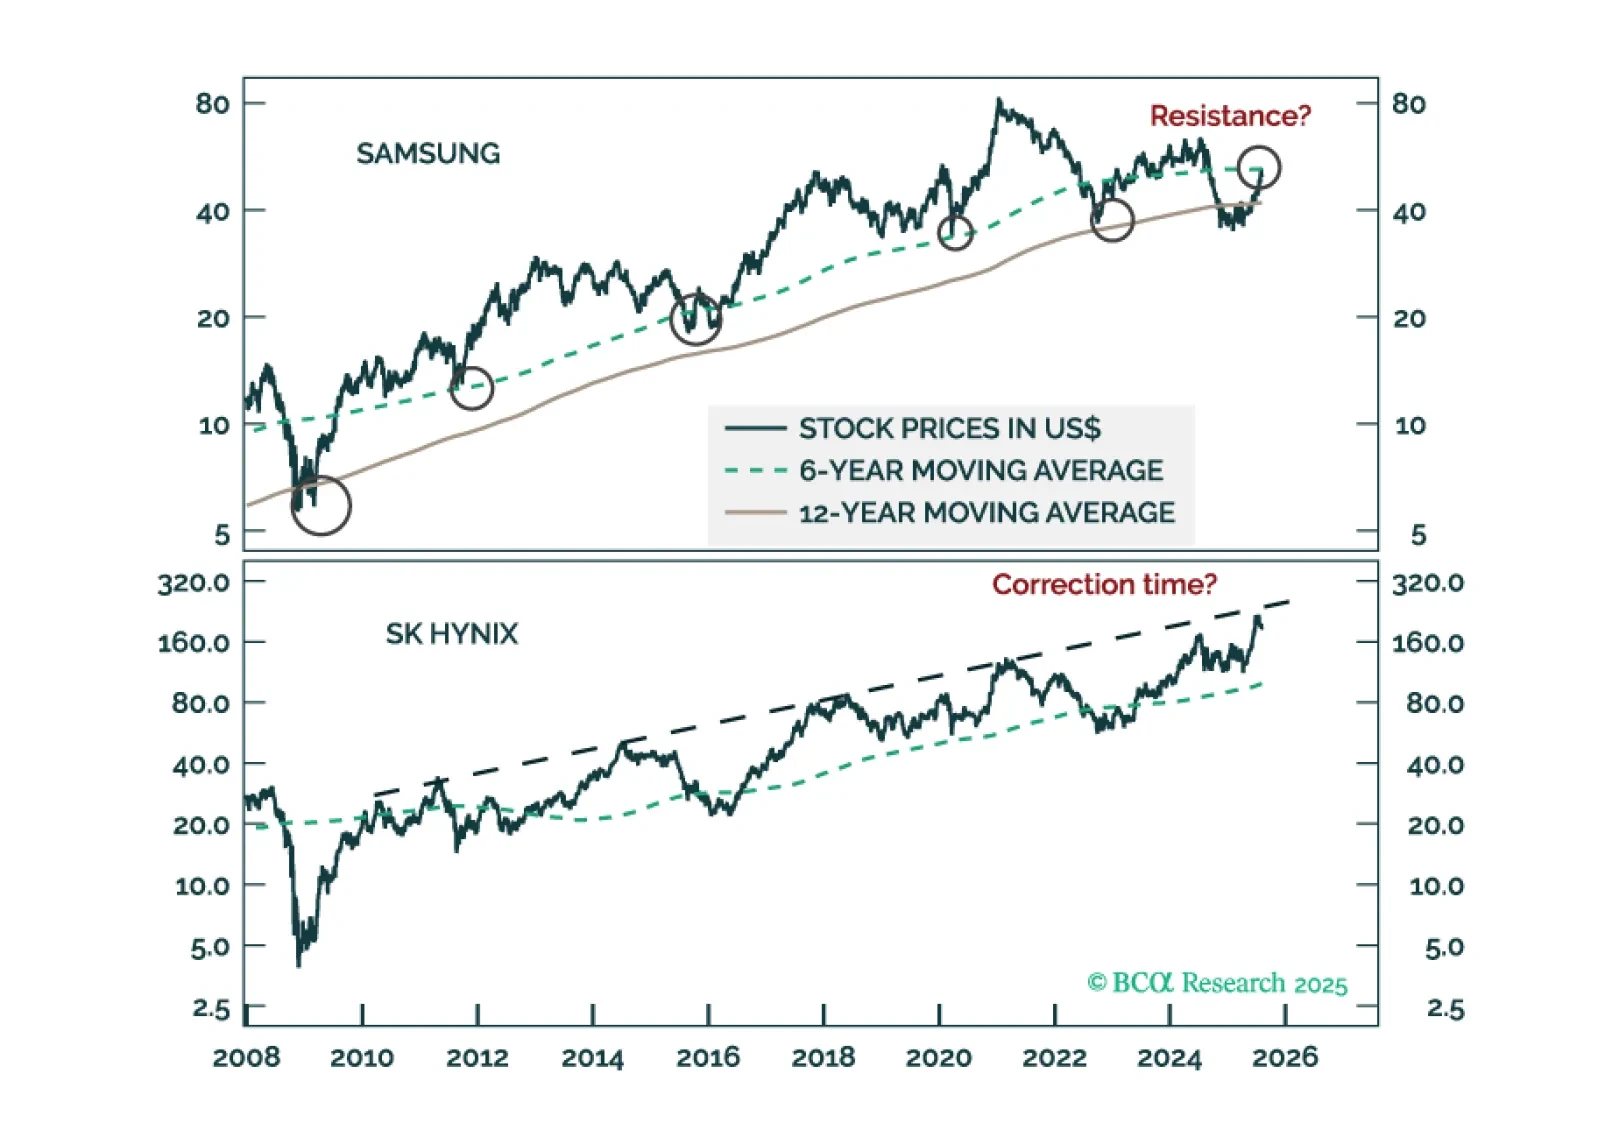
A deflationary shock from shrinking exports will ripple throughout the Korean economy. We are downgrading the KOSPI from overweight to neutral and reiterating a long position in 10-year domestic bonds, currency unhedged.