Latest from BCA Research

The bond vigilantes are circling over several targets right now: France, the UK, and Japan. But France is the most vulnerable because of a toxic combination: a total debt ratio well above 300 percent plus the worst primary deficit in the G7 plus political gridlock, which will get even worse if Prime Minister Francois Bayrou loses the September 8th vote of confidence in his minority government. We explain why the ECB cannot save France, and the investment implications. Plus, we unveil our brand-new complexity ‘heat map’ for global asset allocation which leads to a new tactical trade to underweight world communication services (WTEL).


I am pleased to announce the launch of PowerTrades, an exclusive new service for Global Investment Strategy subscribers that delivers our top trading insights directly to your inbox.

Renewables’ role in power-hungry data centers is overstated. Natural gas will fill clean electricity’s data center supply shortfall, particularly in the US and Europe.
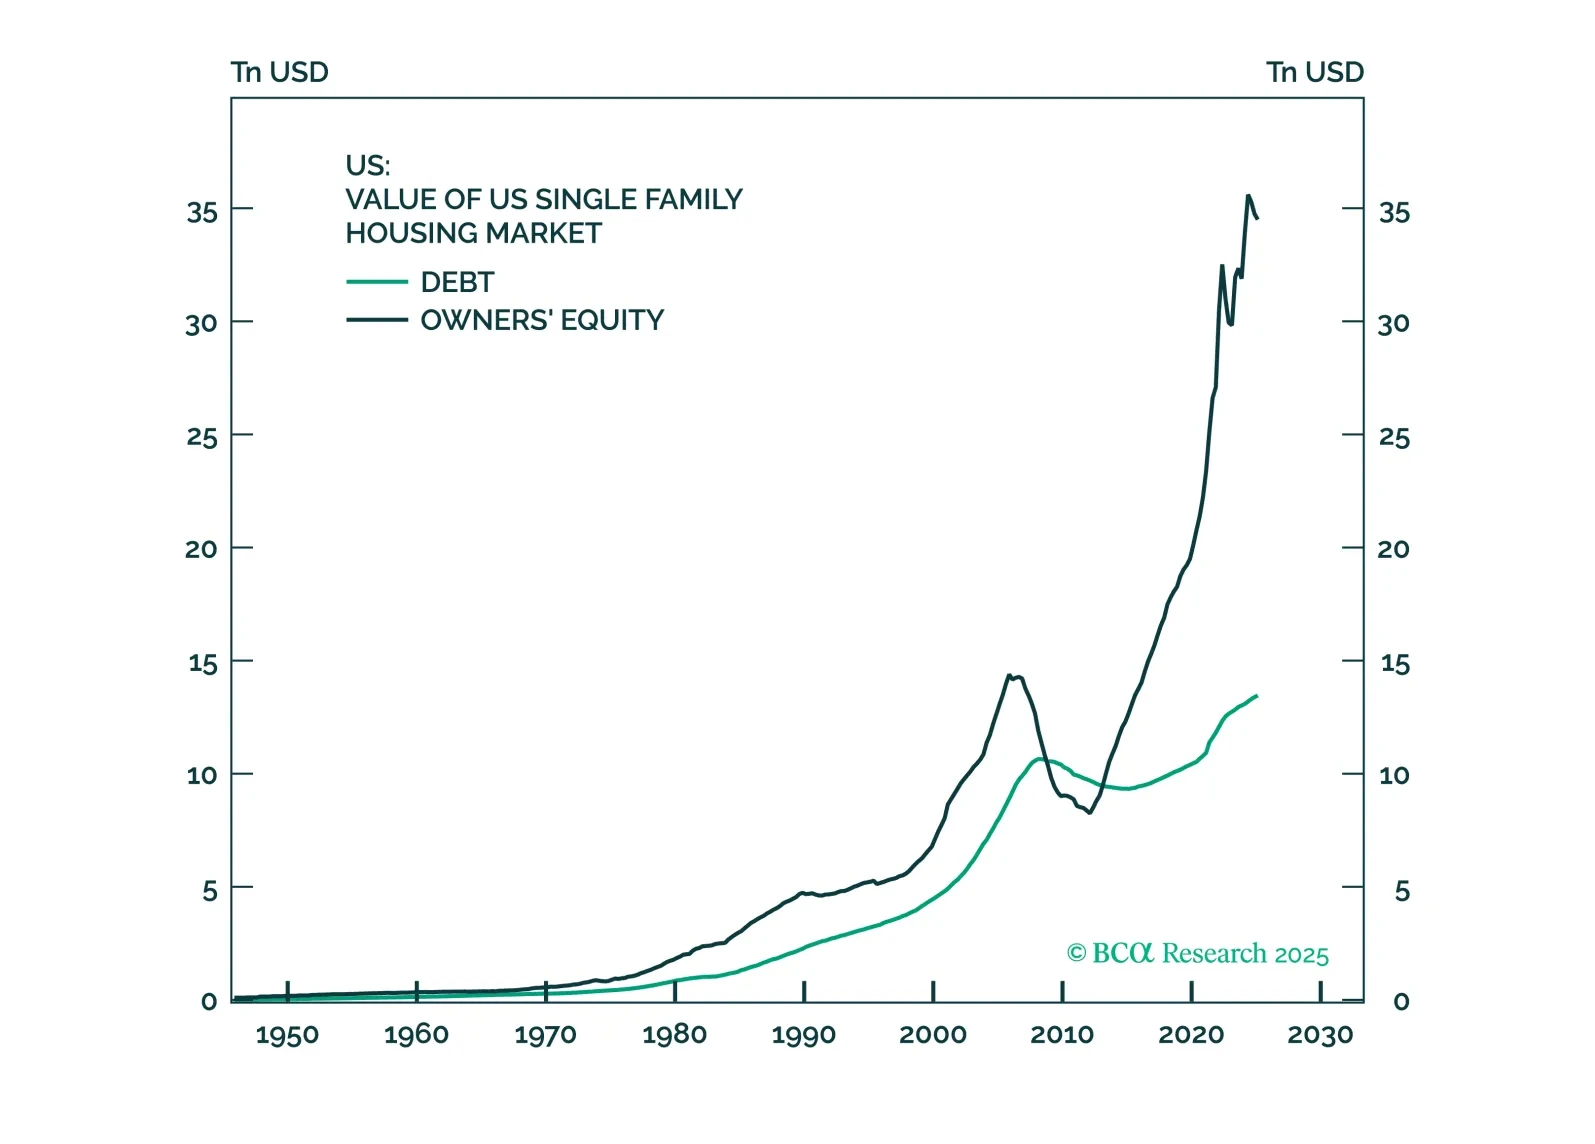
In the Alpha report, we maintain our bullishness on the equity market. We are optimistic that the cash-fueled cycle will evolve into a leverage-driven one, with the AI capex cycle acting as the "bridge" between the two. Our view is easily falsifiable. If the 10-year yield starts moving against us, we will pull the plug on the cycle. One reason to fret is that tariff revenue has now become critical to the equity bull market. Without it, bonds could riot.
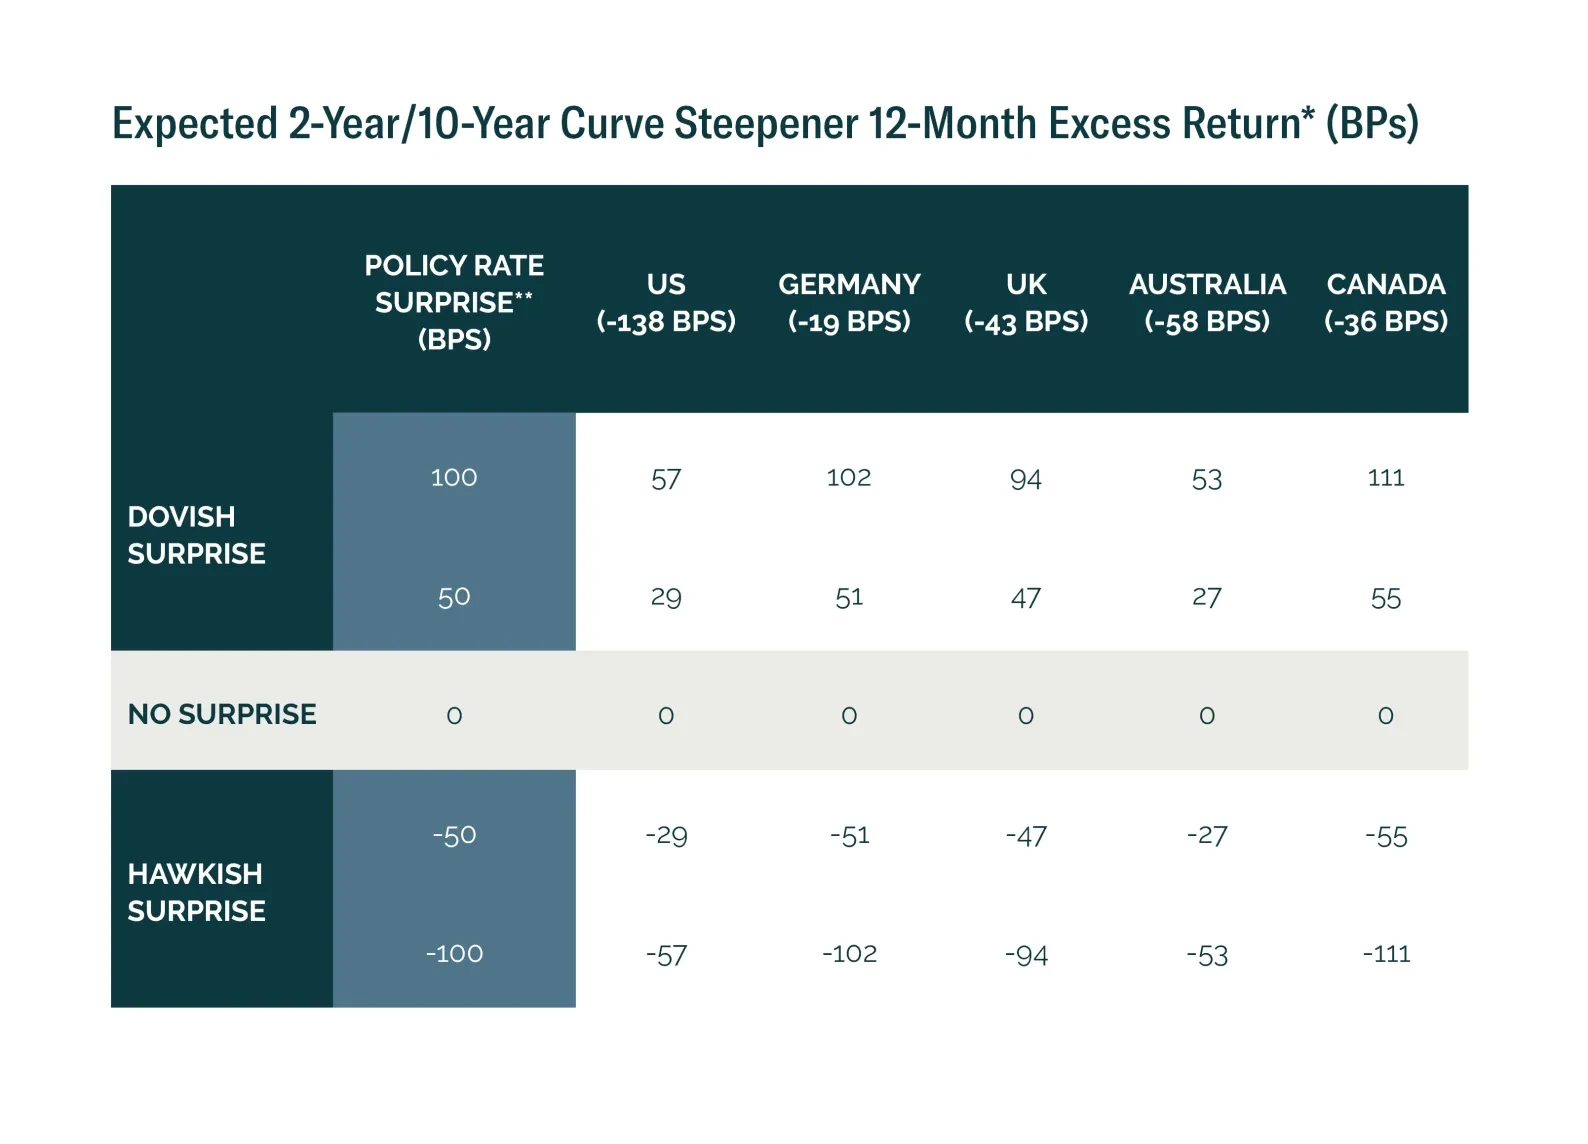

Political instability will persist in France as PM François Bayrou loses the confidence vote. The nomination of a new PM will not end the country’s political paralysis and will further fuel fiscal fears. Investors should remain underweight French OAT. French equities, especially French banks, should be bought on dips.
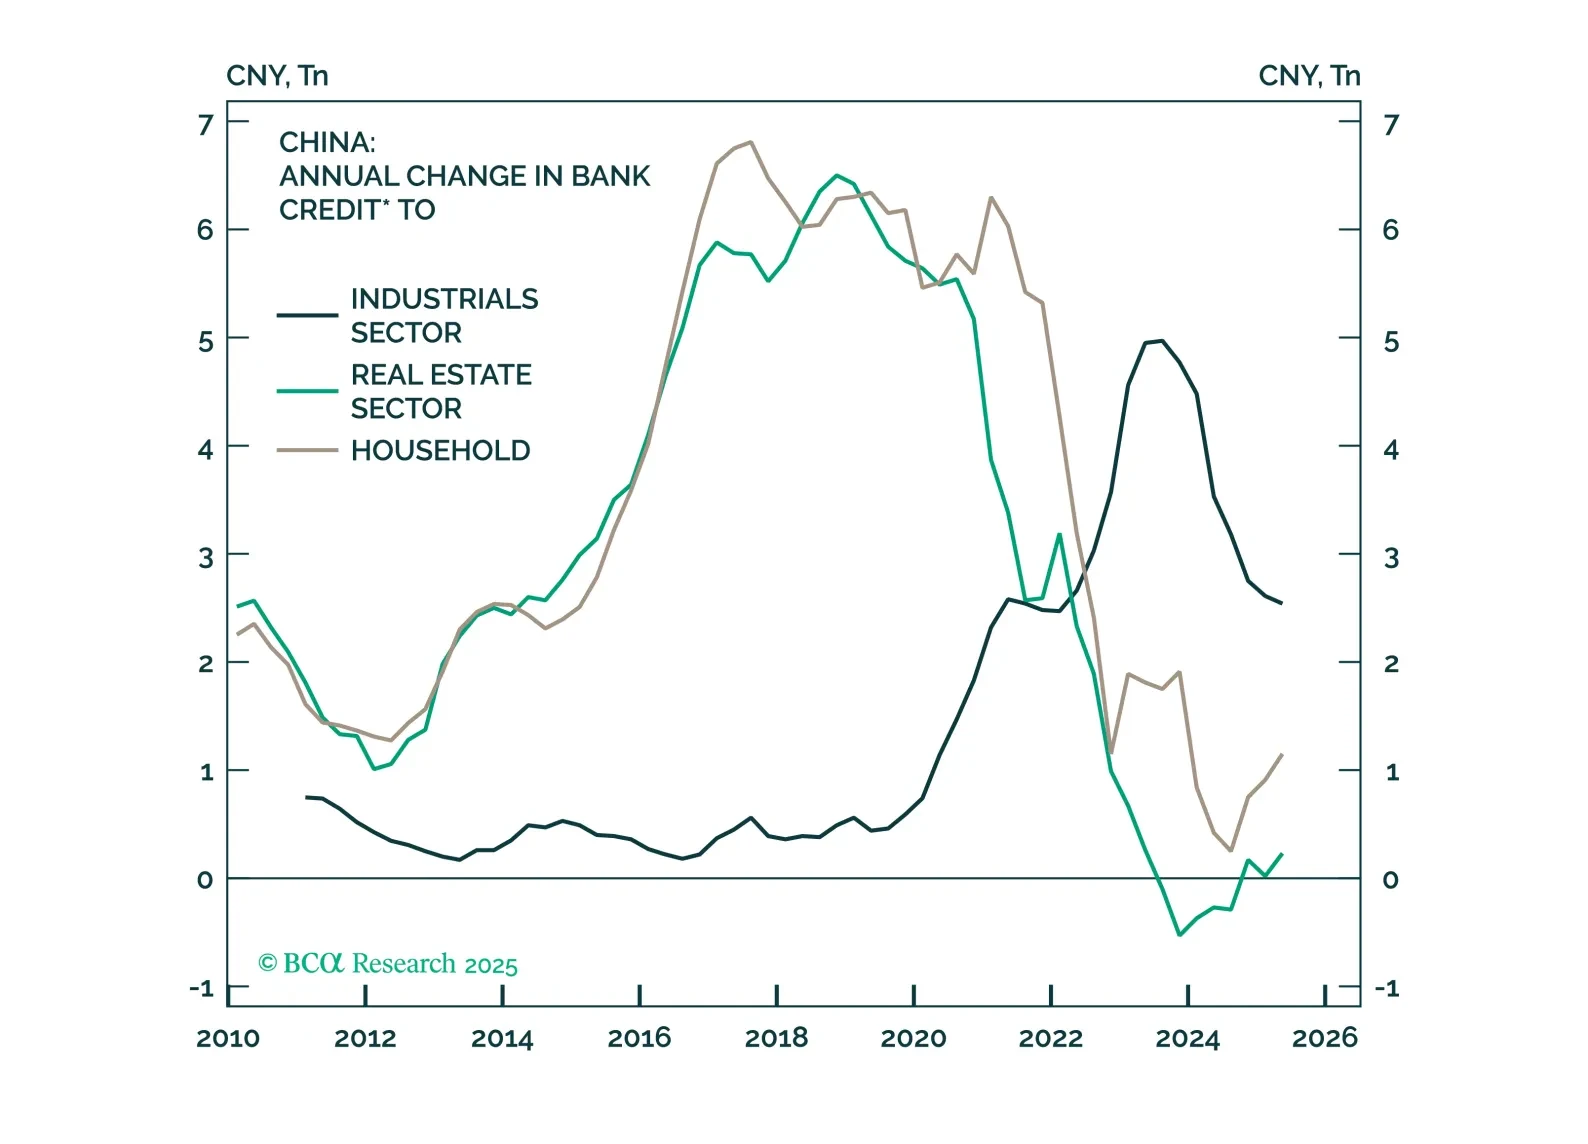
The US overconsumes and underproduces. China overproduces and underconsumes. There are early signs that this decades-old imbalance has peaked and is beginning to reverse. Upgrade the CNY to overweight.

MacroQuant sees downside risks to stocks over a long-term horizon but is not yet saying that we are at imminent risk of an equity bear market.
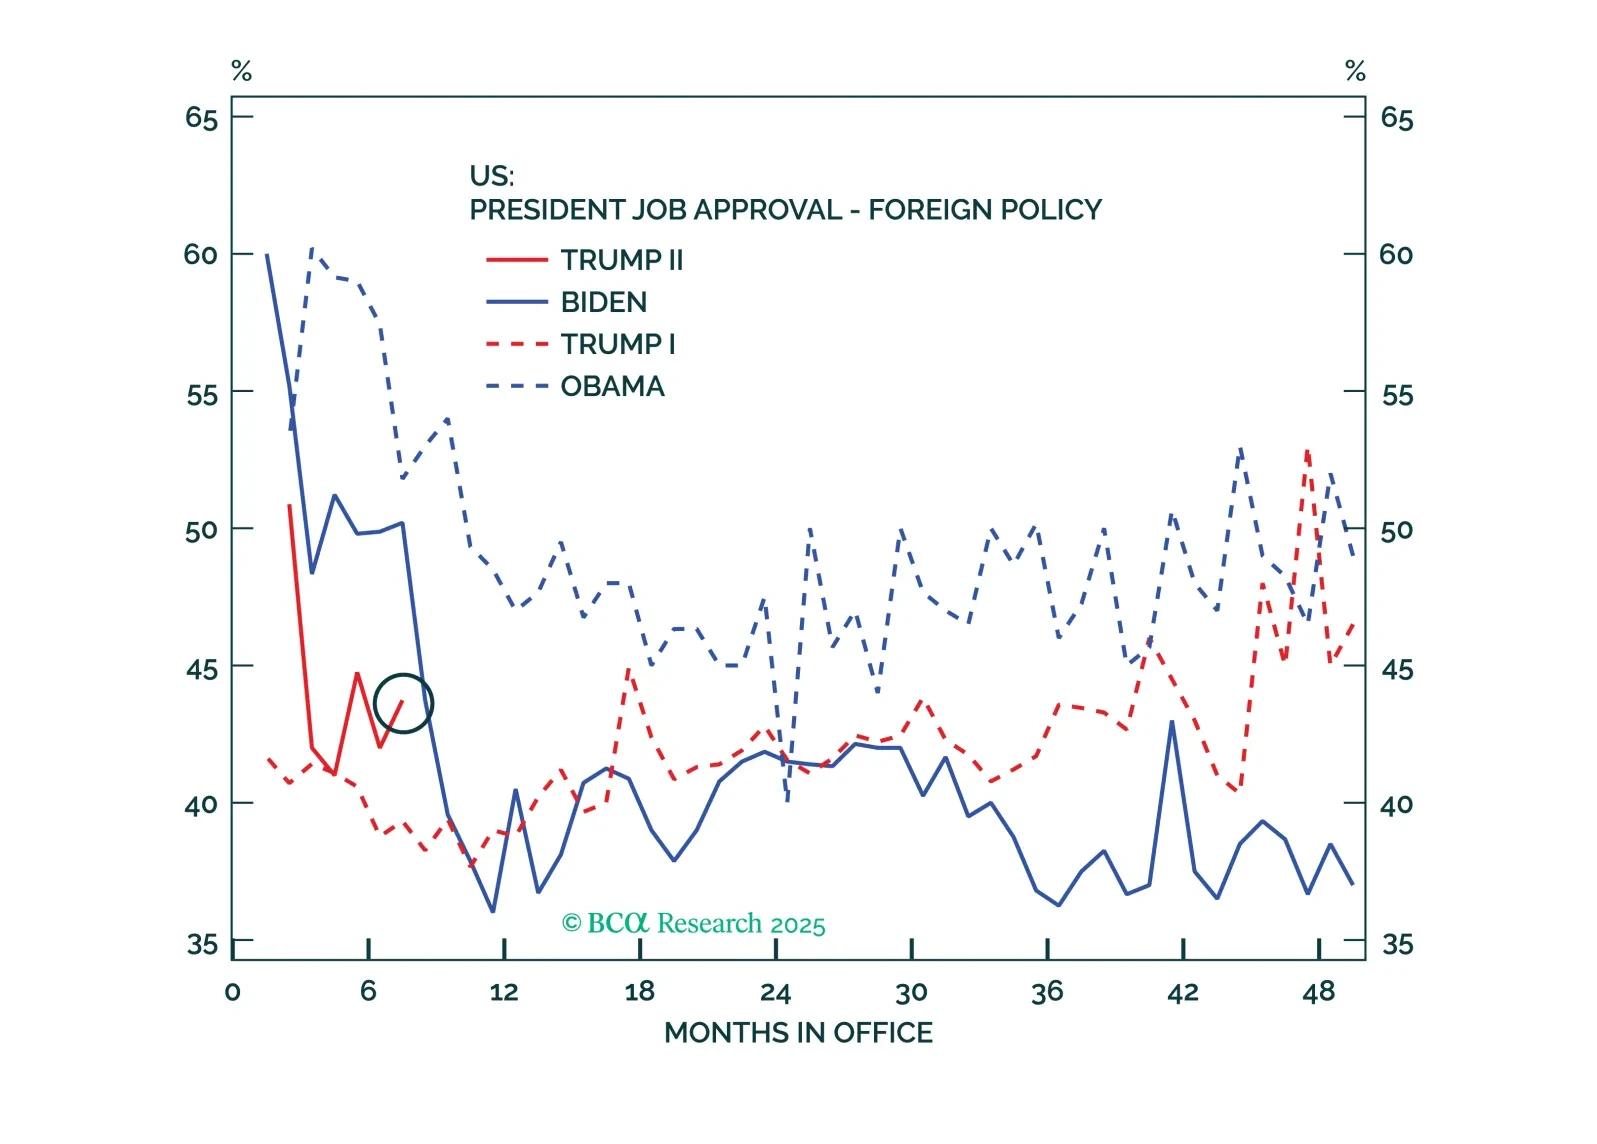
Trump, the Fed, the Russo-China bloc, Venezuela, and France are all seeing developments that imply some contrarian tactical views: Long USD, overweight US versus Europe, overweight Europe versus China, and short oil.