 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.

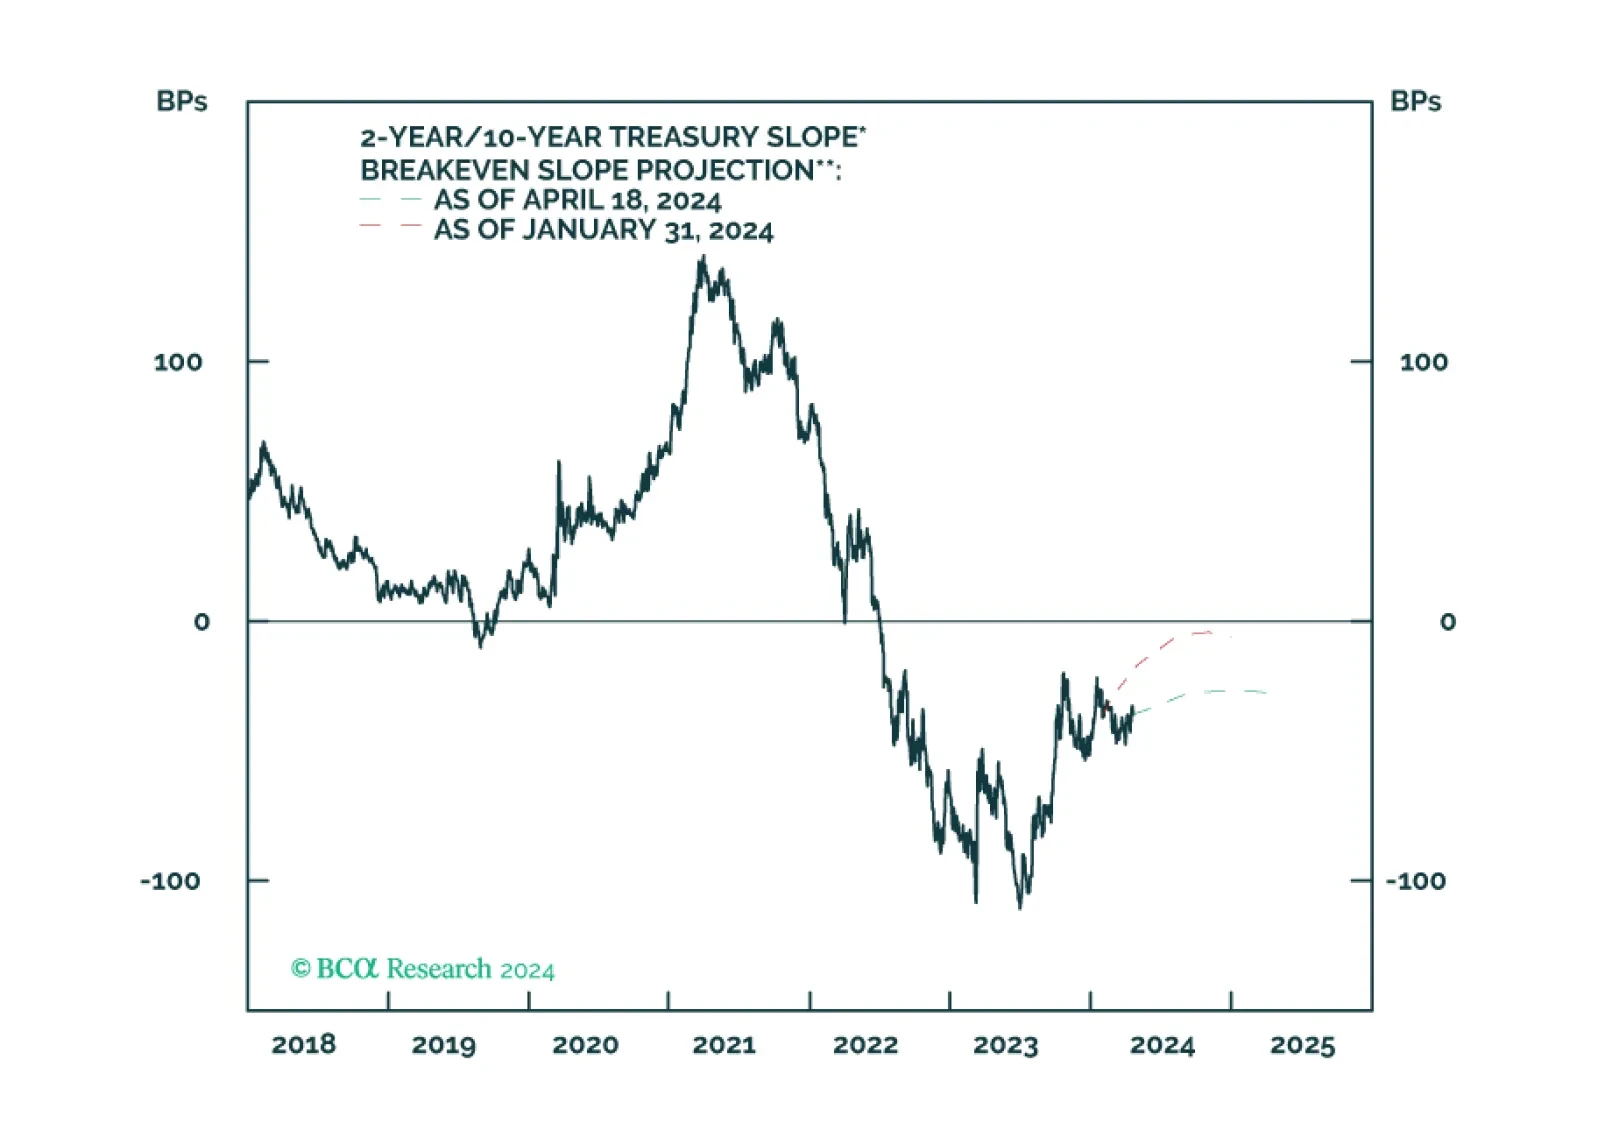
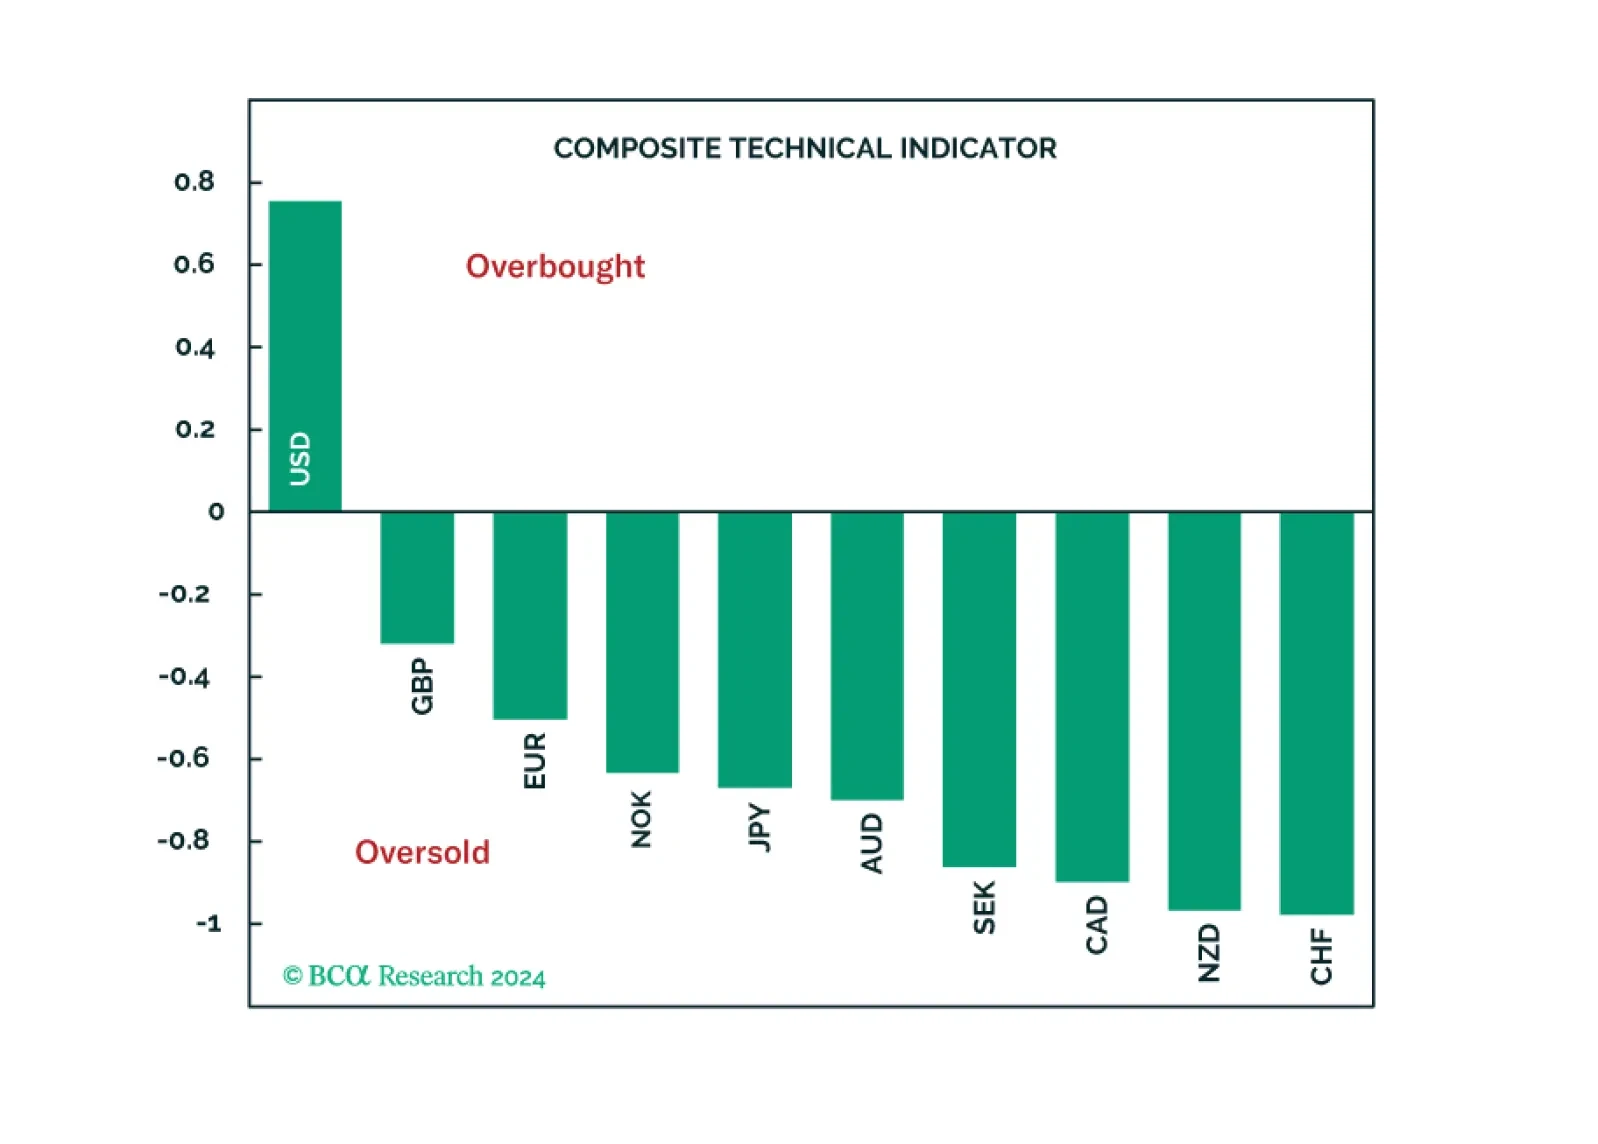
In this report, we review what our technical indicators are telling us about the G10 currencies.

Strong growth in the US and large EMs ex-China will translate into higher oil demand in 2024 – 2025. With mostly unchanged oil supply, tighter markets will ensue. We’ve raised our 2024 average Brent forecast to $98/bbl, and expect $105/bbl in 2H24. In 2025, we expect Brent to average $110/bbl. Prices could easily move higher, if the US moves against one or all of the states enjoying US sanctions forbearance – Russia, Iran, Venezuela. If Brent trades through $110/bbl, Saudi Arabia and the UAE will release spare capacity.

In this report, we present our quarterly review of our Model Bond Portfolio. The anti-growth bias of the portfolio allocations hurt the portfolio performance in Q1/2024 as global growth surprised to the upside. However, we anticipate some recovery of the underperformance in our base case scenario for the next six months.

At today’s monetary policy meeting, the ECB gave strong hints that rate cuts will begin as soon as the next meeting in June. In this Insight, we share our thoughts on today’s meeting and discuss the implications for European bond yields and the euro.

Our bullish gold, copper and oil calls have played out as expected, with gains of 14%, 11% and 16% since the beginning of the year. In this risk assessment of our views, we conclude the bull trends driving these markets higher remain intact. However, the risks of central-bank policy errors, resource nationalism and protectionism are rising. We are raising our gold and copper price targets to $2,500/oz (from $2,300/oz) and $5.00/lb (from $4.50/lb).
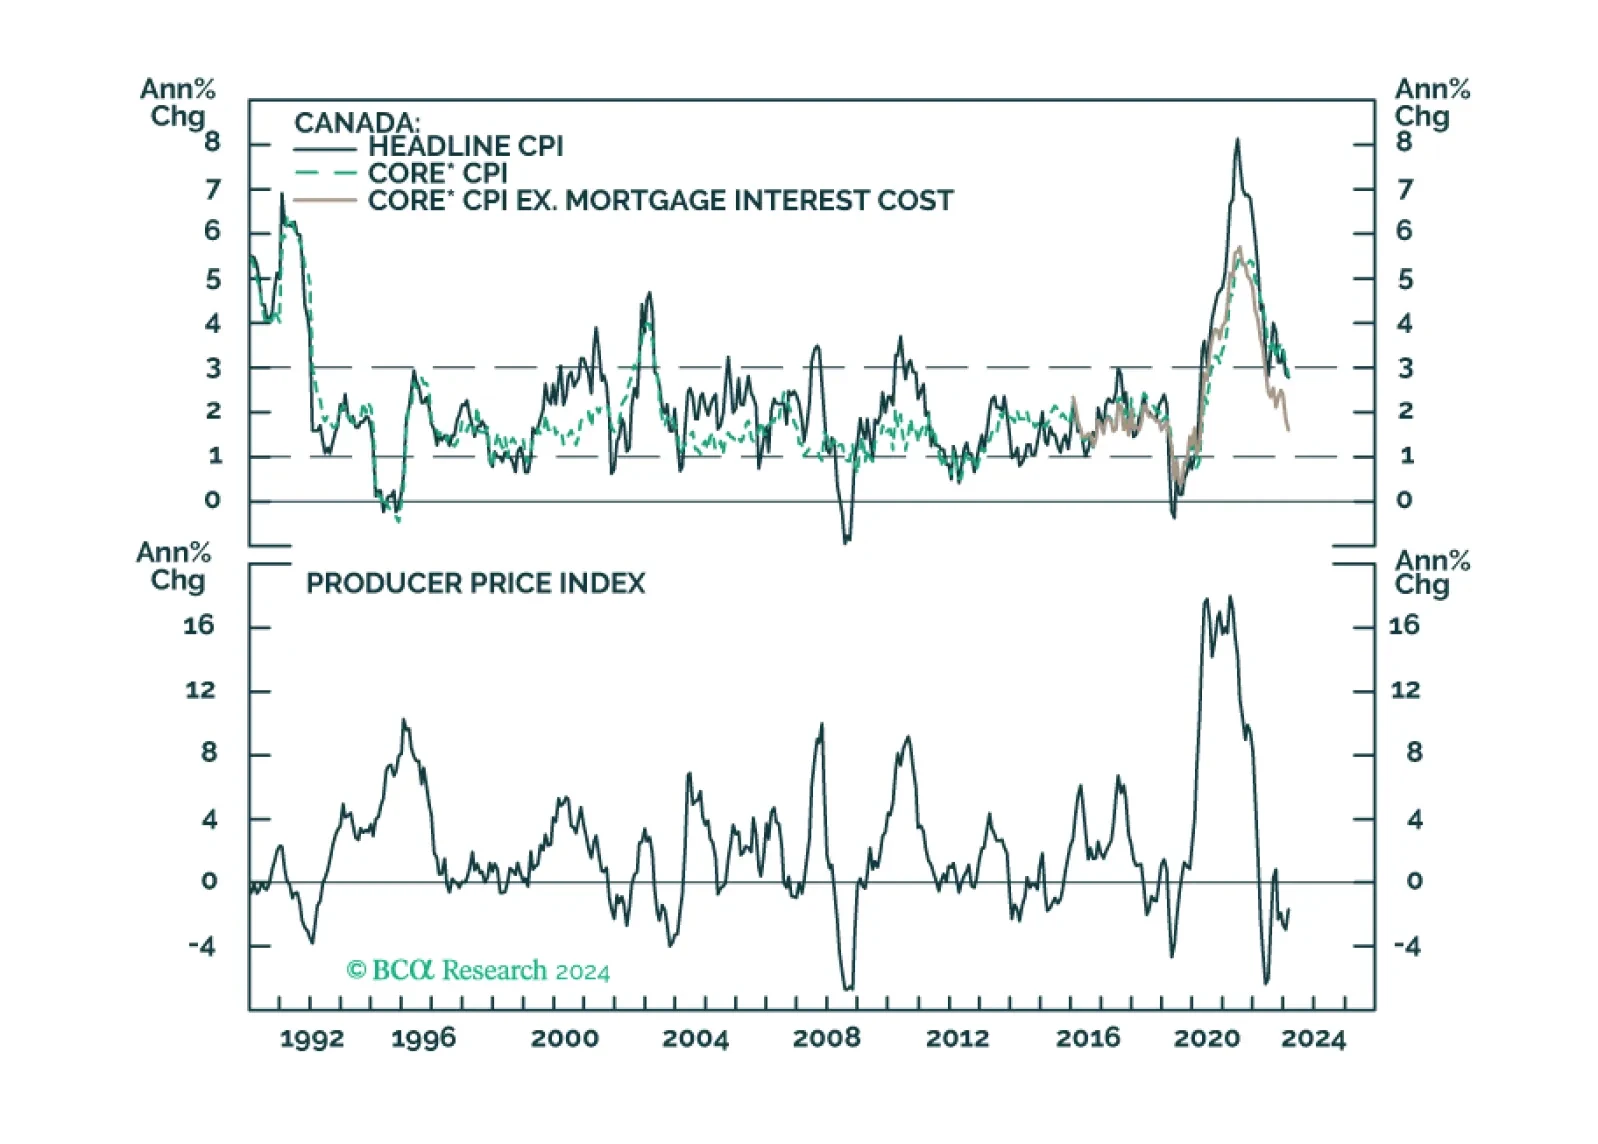
In this insight, we calibrate our investment views based on the latest Bank of Canada decision.
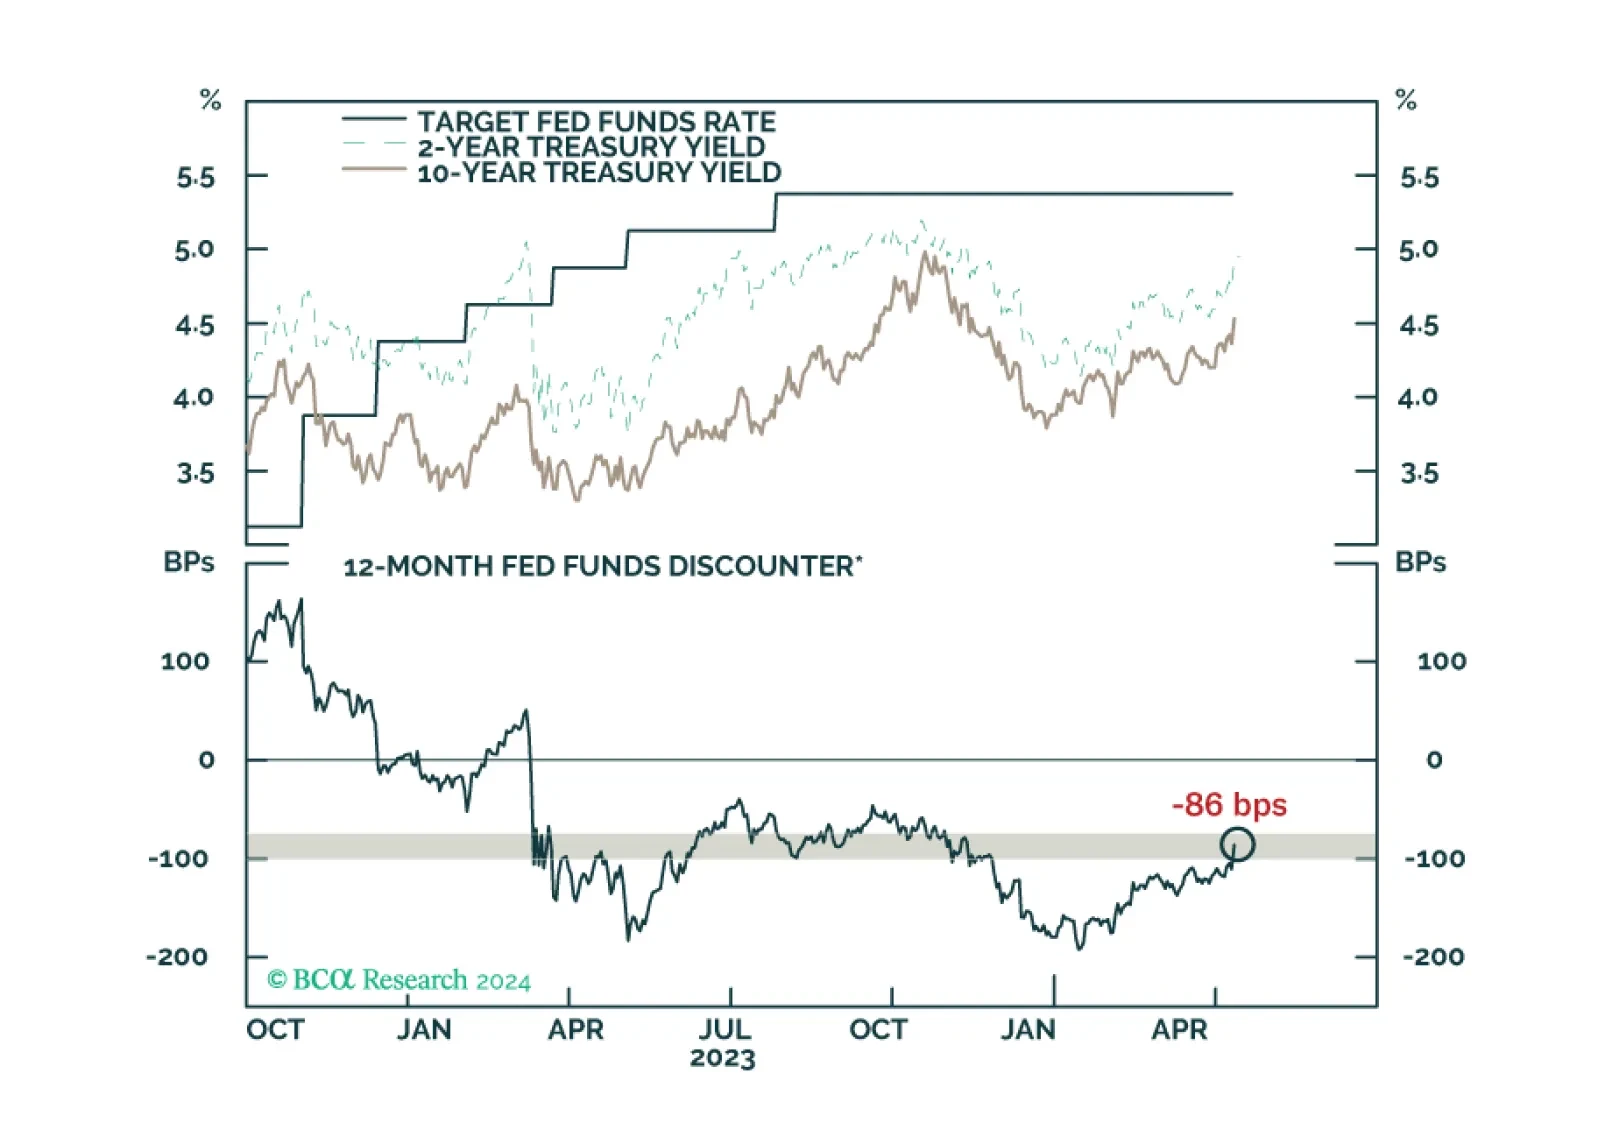
Our reaction to this morning’s CPI report and bond market moves.

Our reaction to this morning’s employment report and bond market moves.